You can afford a bungalow in Ontario sooner by combining several strategies: stacking tax-advantaged savings like the FHSA and RRSP Home Buyers’ Plan, using rental income from a legal suite, buying with family, and searching in areas or styles with better value. No single trick does it all. Together, these eight strategies can close the gap between your budget and the bungalow you want.
Key takeaways
- Get pre-approved first so you know your real budget under the stress test.
- You can combine the FHSA and the RRSP Home Buyers’ Plan for one purchase.
- A legal basement unit can help you carry the mortgage.
- Bungalow townhomes, raised bungalows and areas outside the core can stretch your dollars.
Build your budget the smart way
The first three strategies are about knowing your true buying power and growing it before you shop.
1. Know your real number with a pre-approval
Lenders qualify you at the higher of your contract rate plus 2% or 5.25%. As of September 2026, typical five-year fixed rates are in the mid-4% range, so many buyers qualify at a rate well above what they’ll pay.
A pre-approval from a mortgage agent shows what you can borrow and holds a rate for a period of time. It also flags credit or debt issues you can fix before you shop. Start with our affordability and mortgage calculators.
2. Stack your tax-advantaged savings
If you’re a first-time buyer, two programs can work together on the same purchase:
- FHSA: $8,000 a year, up to $40,000 lifetime per person. Contributions are tax-deductible and qualifying withdrawals are tax-free.
- RRSP Home Buyers’ Plan: withdraw up to $60,000 per person, repaid over 15 years.
A couple who each max out both could put a large sum toward a down payment, partly funded by tax refunds along the way. For a full savings plan, read saving for a bungalow down payment.
3. Choose the right amortization
A longer amortization lowers your monthly payment. First-time buyers and buyers of newly built homes can get a 30-year amortization on an insured mortgage. Other insured buyers are limited to 25 years. With 20% or more down, many lenders offer 30 years too.
The trade-off is more interest over time. Many owners choose 30 years for flexibility, then make extra payments when they can.
Bring in extra income or help
4. Let a basement suite help pay the mortgage
Ontario allows up to three residential units on most serviced urban lots, such as a main house, a basement unit and a garden suite. A legal basement apartment in a raised bungalow can bring in steady rent.
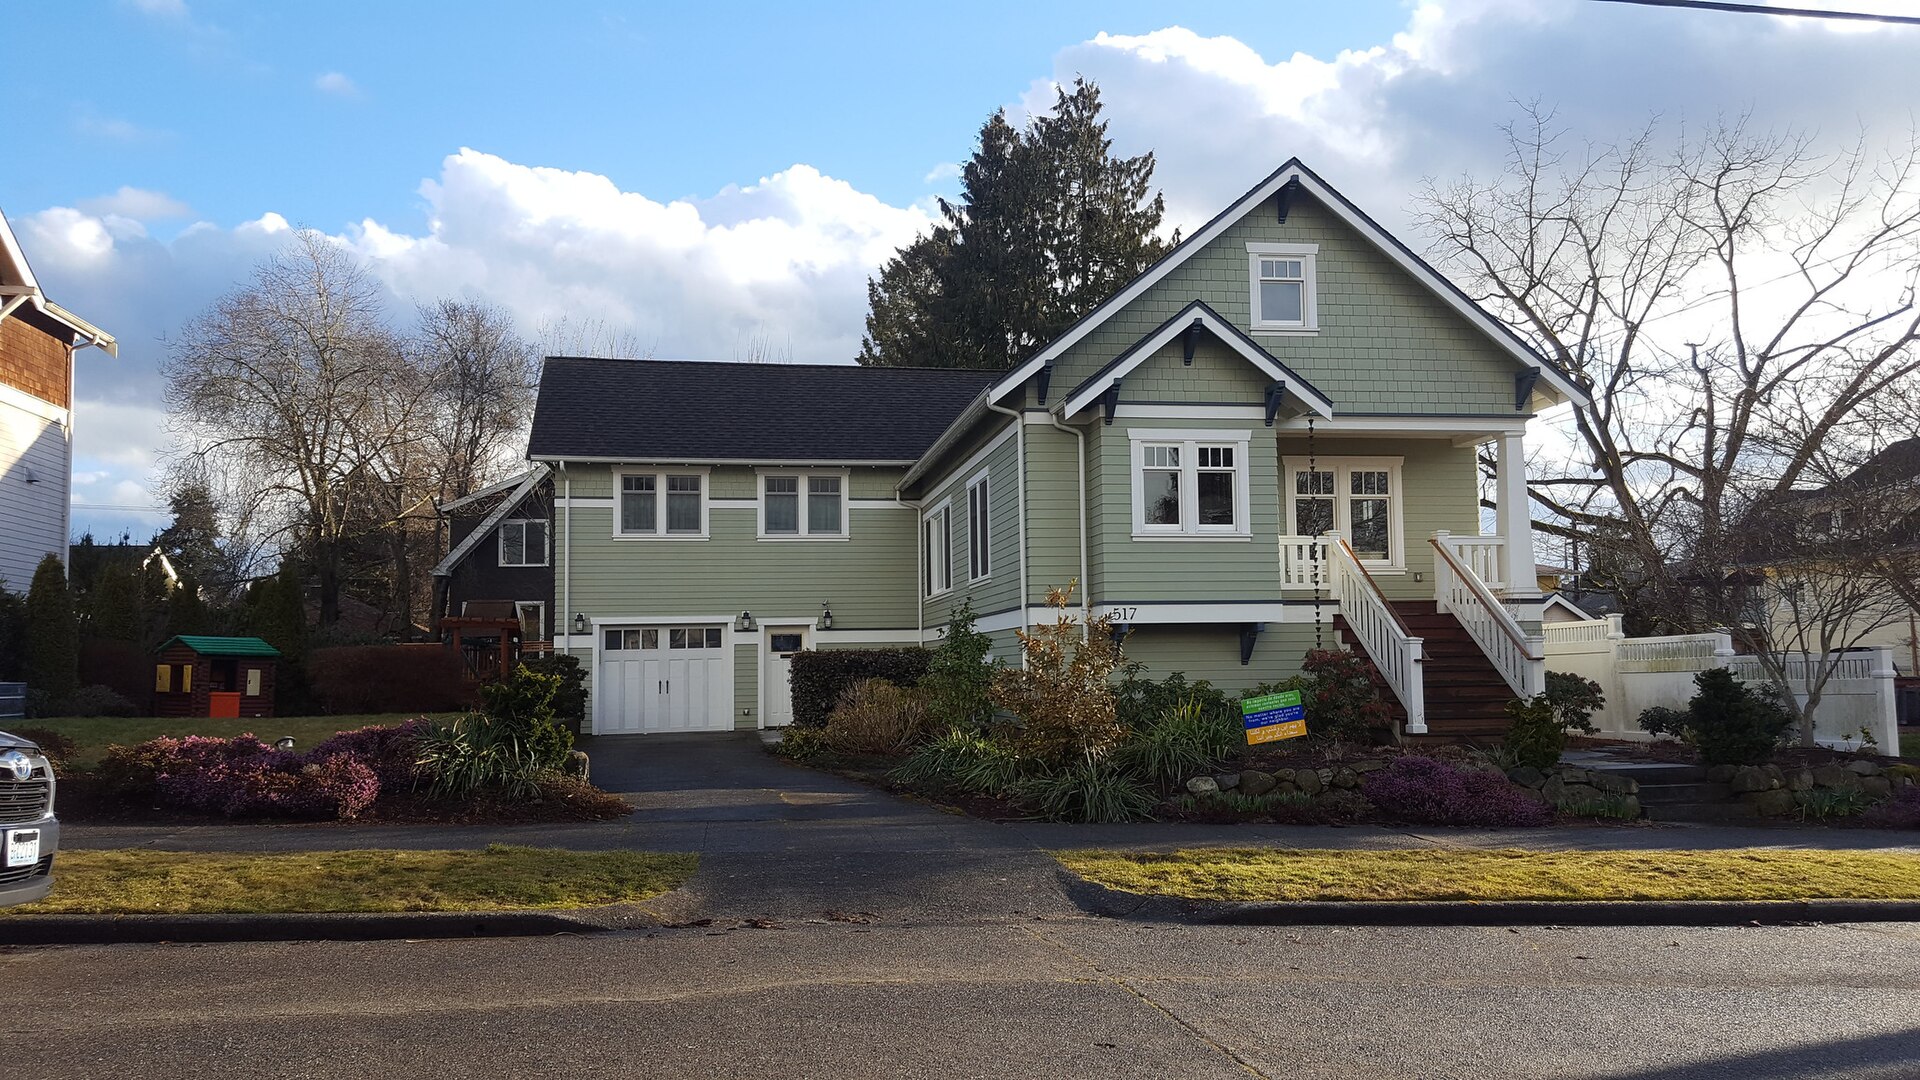
Keep in mind that a legal unit needs permits, fire separation, egress windows and a proper entrance. Ask your mortgage agent how lenders treat rental income. Learn the basics in our guide to house hacking.
Bungalow tip: Raised bungalows with large basement windows and a side door are often the easiest to convert to a legal second unit. Ask for permit history before you buy.
5. Buy with family
Multigenerational buying is common in the GTA. Parents and adult children pool savings and incomes to buy a bungalow with space for everyone. Family members can also gift money toward a down payment, usually with a signed gift letter.
Co-owning works best with a written agreement on who pays what and what happens if someone wants out. Talk to a real estate lawyer before you sign.
Shop where your money goes further
6. Widen your search by area and style
| Option | Why it can cost less | Trade-off |
|---|---|---|
| Bungalow townhome | Attached, less land | Shared walls and possible fees |
| Condo bungalow | Shared land and upkeep | Monthly condo fees |
| Older raised bungalow | Dated finishes | Updates needed over time |
| Durham, Hamilton, Niagara or Brantford | Lower prices than central Toronto | Longer commutes for some |
Buying outside the City of Toronto also means you won’t pay Toronto’s municipal land transfer tax. Browse affordable bungalows for sale to see where your budget goes furthest.
7. Consider a fixer-upper
A dated bungalow on a good lot can cost less than a renovated one nearby. Update it over time as your budget allows. Get an inspection and contractor quotes before you buy, and keep a cushion for surprises.
Claim every first-time buyer benefit
8. Use the programs you qualify for
First-time buyers can also claim the federal First-Time Home Buyers’ Tax Credit of up to $1,500 and the Ontario land transfer tax refund of up to $4,000. Inside Toronto, add the municipal rebate of up to $4,475. These help with closing costs, which typically run 1.5% to 4% of the price.
Remember that the new-home GST and HST rebates apply only to newly built homes, not resale bungalows. If you’re open to a new build, ask your lawyer whether you qualify.
Frequently asked questions
Can I use the FHSA and the Home Buyers’ Plan together?
Yes. As a first-time buyer, you can use both for the same home purchase, as long as you meet each program’s rules.
What’s the minimum down payment on a bungalow?
It’s 5% on the first $500,000 and 10% on the portion from $500,000 to $1,499,999. Homes at $1.5 million or more need 20% down.
Can rental income help me qualify for a mortgage?
Often, yes, if the unit is legal or will be. Lenders use different rules, so ask a mortgage agent before you shop.
The bottom line
Buying a bungalow is easier when you combine strategies instead of relying on one. Save in the right accounts, choose a smart mortgage structure, consider income or family help, and look beyond the most expensive areas.
This is general information. Talk with a mortgage agent and an accountant about your own situation before you make big decisions.
Bungalows for sale in Toronto right now
Live listings from the area this article covers.
 $1,500,00097 Estelle Avenue, Toronto3+4 bed · 7 bath · Willowdale EastCourtesy of RE/MAX REALTRON REALTY INC.
 $699,0007 Twenty Second Street, Toronto3+3 bed · 3 bath · Long BranchCourtesy of RE/MAX PREMIER INC.
 $945,000257 John Tabor Trail E, Toronto3+2 bed · 2 bath · MalvernCourtesy of RE/MAX ATRIUM HOME REALTY
 $1,145,000109 Gulliver Road, Toronto4 bed · 3 bath · Brookhaven-AmesburyCourtesy of RE/MAX REALTY SPECIALISTS INC.
 $1,398,80074 Navaho Drive, Toronto3+4 bed · 3 bath · Pleasant ViewCourtesy of HOMELIFE LANDMARK REALTY INC.
 $2,990,00061 Highland Crescent, Toronto2+1 bed · 2 bath · Bridle Path-Sunnybrook-York MillsCourtesy of RE/MAX REALTRON BARRY COHEN HOMES INC.