Home insurance in Ontario protects your house, your belongings and you from financial loss after events like fire, theft, wind damage and some kinds of water damage. It also covers your liability if someone is hurt on your property. It is not legally required, but your mortgage lender will require proof of coverage before closing, so you need a policy lined up before you get the keys.
Key takeaways
- Lenders require home insurance before they release mortgage funds.
- Standard policies often exclude sewer backup and overland flooding unless you add them.
- The age of the roof, wiring, plumbing and heating affects your premium.
- Tell your insurer about any basement rental suite.
- An insurance broker can compare several insurers for you.
What does home insurance cover?
Most Ontario homeowner policies combine four main types of coverage:
- Dwelling: the house itself, including built-in features like cabinets and flooring.
- Detached structures: sheds, detached garages and fences.
- Contents: furniture, clothes, electronics and other belongings.
- Additional living expenses: hotel and meal costs if a covered loss forces you out.
- Personal liability: legal and medical costs if you are responsible for someone’s injury or damage to their property.
Coverage limits, deductibles and exclusions vary by insurer and policy. Always read the policy wording, not just the summary.
Types of home insurance policies
| Policy type | What it covers | Good for |
|---|---|---|
| Comprehensive | All risks to the home and contents, except listed exclusions | Most owners who want the broadest protection |
| Broad | All risks to the dwelling; named perils for contents | Balancing cost and coverage |
| Basic or named perils | Only the specific perils listed | Tight budgets, but with bigger gaps |
| No-frills | Very limited coverage | Homes that cannot qualify for standard coverage |
Condo bungalow owners buy a condo unit policy instead. It covers your unit’s improvements, your contents and your share of certain condo corporation costs.
Water damage: the coverage most owners need to check
Water is one of the most common causes of home insurance claims in Ontario. It is also the area where owners are most often surprised by what is not covered.
Common water coverages
- Sudden and accidental water escape: such as a burst pipe. Usually included in comprehensive policies.
- Sewer backup: water backing up through floor drains. Often an optional add-on.
- Overland water: flooding from heavy rain or rising water entering at ground level. Usually a separate add-on, where available.
- Groundwater seepage: slow seepage through foundation walls. Often excluded.
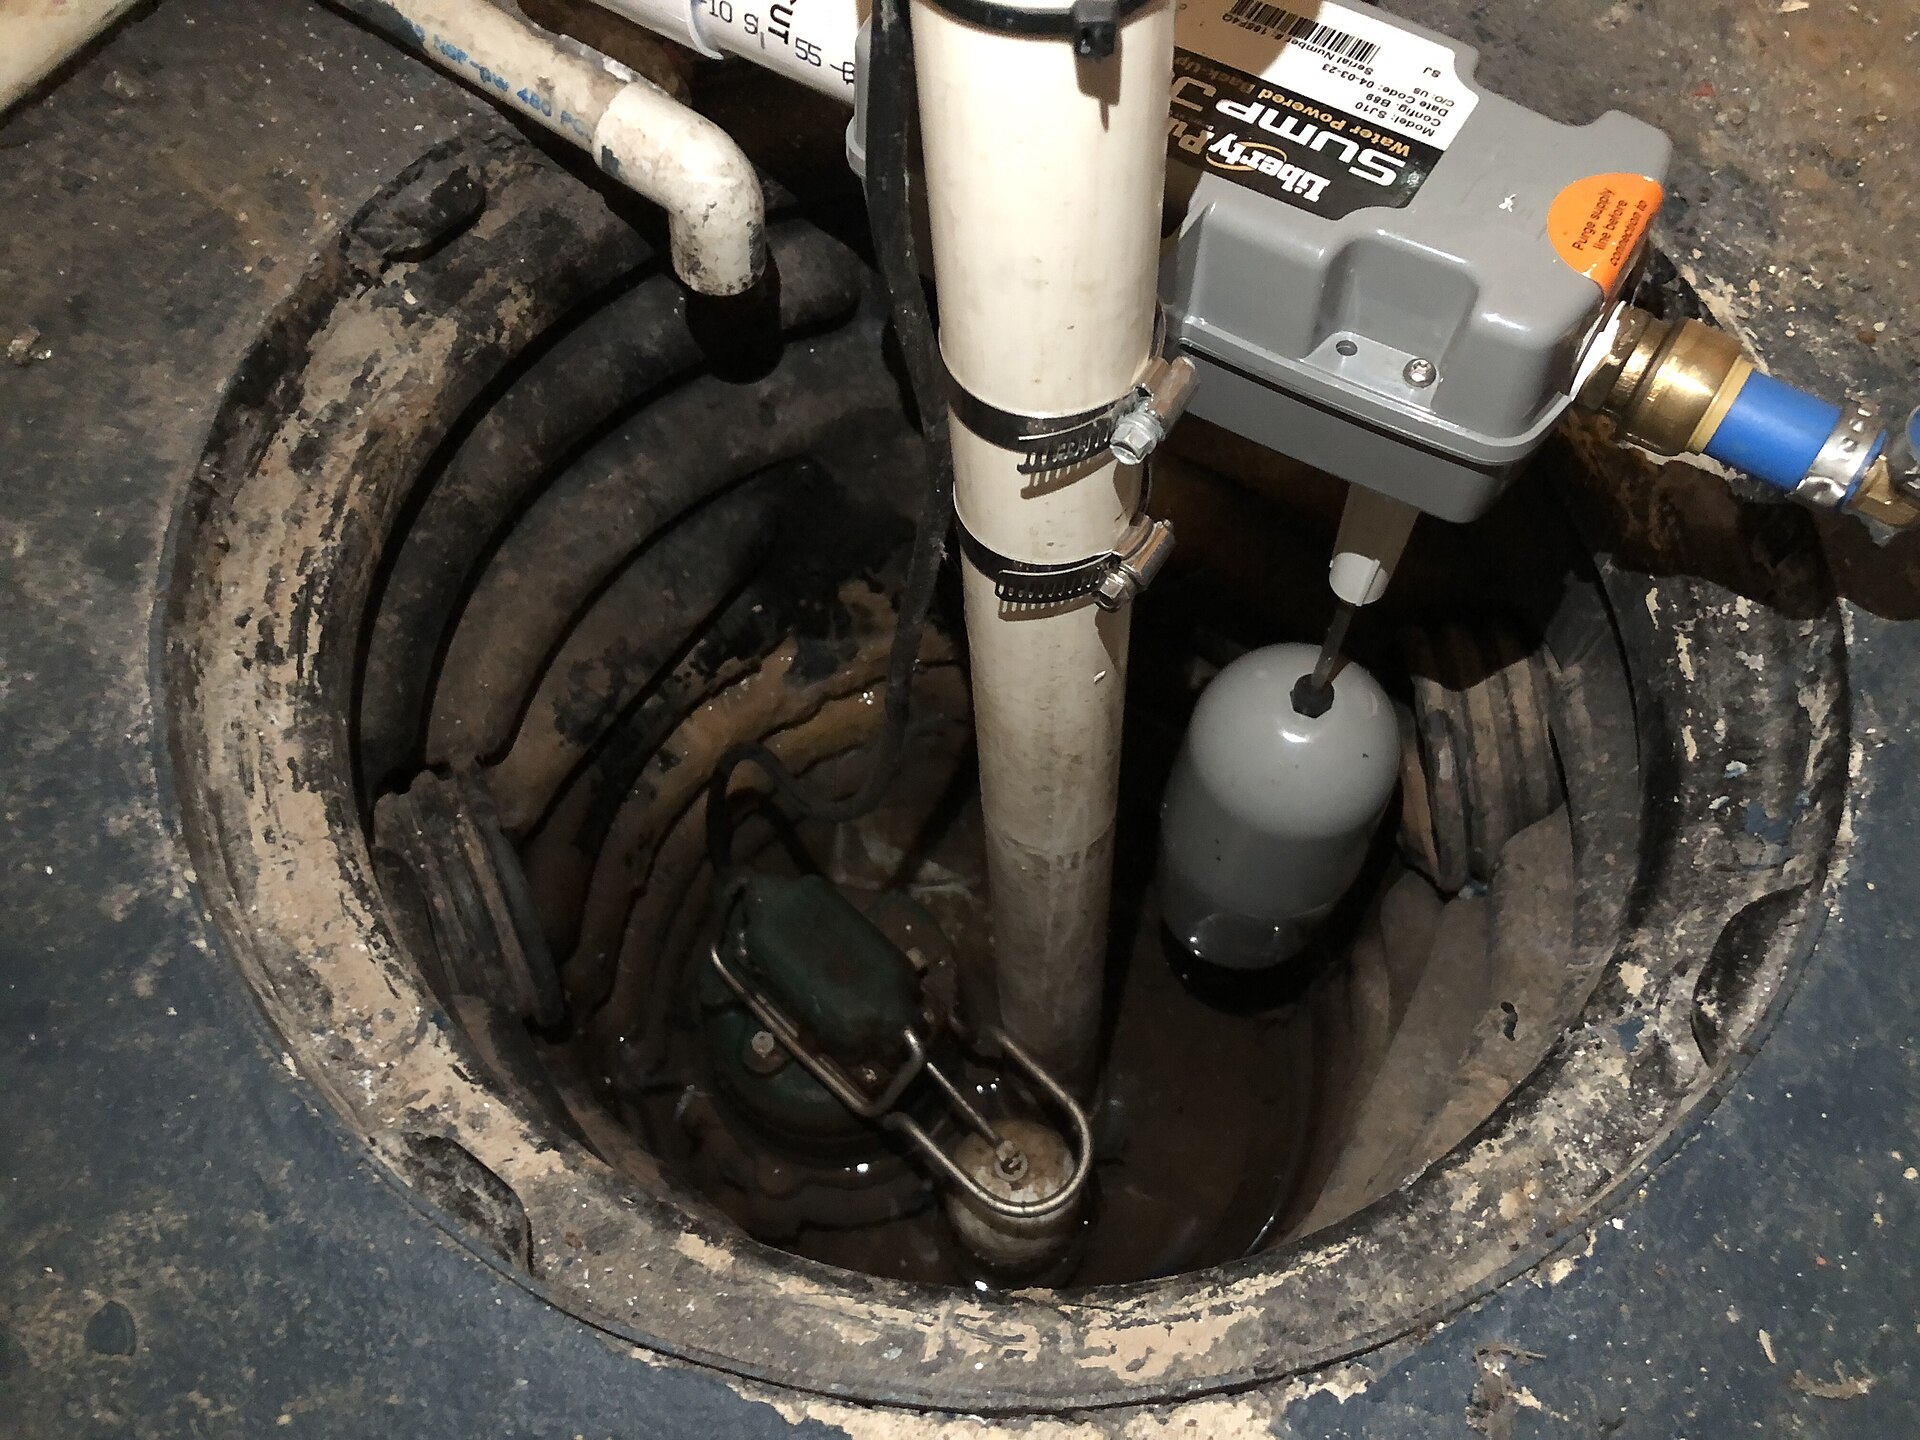
Many bungalows have finished basements, so these add-ons matter. A backwater valve and a working sump pump may help you qualify for coverage or a discount.
Bungalow tip: Ask your broker what proof they need of a backwater valve, sump pump or leak shut-off system. Keep receipts and photos in your home records.
What affects your home insurance premium?
Insurers look at the risk of a claim. Factors include:
- Age and condition of major systems: roof, electrical, plumbing and heating.
- Wiring type: older knob-and-tube or aluminum wiring may limit coverage.
- Heating: wood stoves and oil tanks often need inspections.
- Location: distance to a fire hydrant and fire hall, and local flood and claims history.
- Claims history: your past claims can raise premiums.
- Rebuild cost: size, materials and finishes.
- Deductible: a higher deductible usually lowers the premium.
Older bungalows can be insured well. Insurers simply want to know the systems have been updated or inspected. Ask sellers for update dates and receipts early in your purchase.
Insuring a bungalow with a basement suite
If you rent out a basement or garden suite, tell your insurer. A standard homeowner policy may not cover rental activity, and an undisclosed suite could put a claim at risk.
- Ask for landlord or rental coverage for the rented unit.
- Confirm liability coverage for tenants and their guests.
- Ask about loss of rental income coverage.
- Require tenants to carry their own tenant insurance.
Our guide to tenant insurance explains what your tenants need.
How to buy home insurance before closing
- Start shopping as soon as your offer is accepted, or before you make it if the home is older.
- Give the broker key details: age of roof, furnace, wiring and plumbing, plus any suite.
- Compare coverage, not just price. Check water add-ons and liability limits.
- Send the insurance binder or confirmation to your real estate lawyer and lender before closing.
- Review your policy every year and after any renovation.
Insurance is one of many closing tasks. Our home buyer’s guide covers the full timeline.
Frequently asked questions
Is home insurance mandatory in Ontario?
It is not required by law, but mortgage lenders require it. Without a mortgage, it is still strongly recommended because a single loss could be devastating.
Does home insurance cover basement flooding?
It depends on the cause and your coverage. Sewer backup and overland water are often separate add-ons, so ask your broker exactly what your policy includes.
Why is it harder to insure an older home?
Insurers want to know that the roof, wiring, plumbing and heating are in good shape. Updates and inspection reports usually make an older home easier to insure.
The bottom line on Ontario home insurance
Good home insurance is about the right coverage, not just the lowest price. Pay close attention to water damage add-ons and tell your insurer about any rental suite.
This article is general information. Speak with a licensed insurance broker or agent about your specific home and needs before you buy a policy.
Bungalows for sale in Ontario right now
Live listings from the area this article covers.
 $499,900257 Ontario Street, Stratford3 bed · 1 bath · StratfordCourtesy of Sutton Group - First Choice Realty Ltd.
 $848,800179 Ontario Street, Brighton2+2 bed · 3 bath · BrightonCourtesy of Royal LePage ProAlliance Realty
 $629,90021 Ontario Street, Orangeville3+1 bed · 2 bath · OrangevilleCourtesy of RE/MAX HALLMARK CHAY REALTY
 $649,9005315 Ontario Avenue, Niagara Falls3+1 bed · 2 bath · 210 - DowntownCourtesy of RE/MAX REALTY SERVICES INC.
 $499,000156 Ontario Street, Burk's Falls1 bed · 2 bath · Burk's FallsCourtesy of RE/MAX Parry Sound Muskoka Realty Ltd
 $579,000409 Ontario Street, Warwick2 bed · 2 bath · WatfordCourtesy of EXP REALTY