Pre-construction can be worth it if you have a flexible timeline, can tie up a deposit for years and want a brand-new bungalow with today’s building standards. It’s riskier if you need to move by a fixed date or are counting on quick price growth. In 2026, new-home tax rebates have made pre-construction more attractive for some first-time buyers.
Key takeaways
- New builds can qualify for GST and HST relief that resale homes don’t.
- Closing dates often move, so build flexibility into your plans.
- Have a real estate lawyer review the agreement before you sign.
- Budget for closing adjustments that resale buyers don’t pay.
What does buying pre-construction mean?
You sign an agreement with a builder for a home that isn’t built yet. You pay a deposit, often in stages, and close when the home is finished.
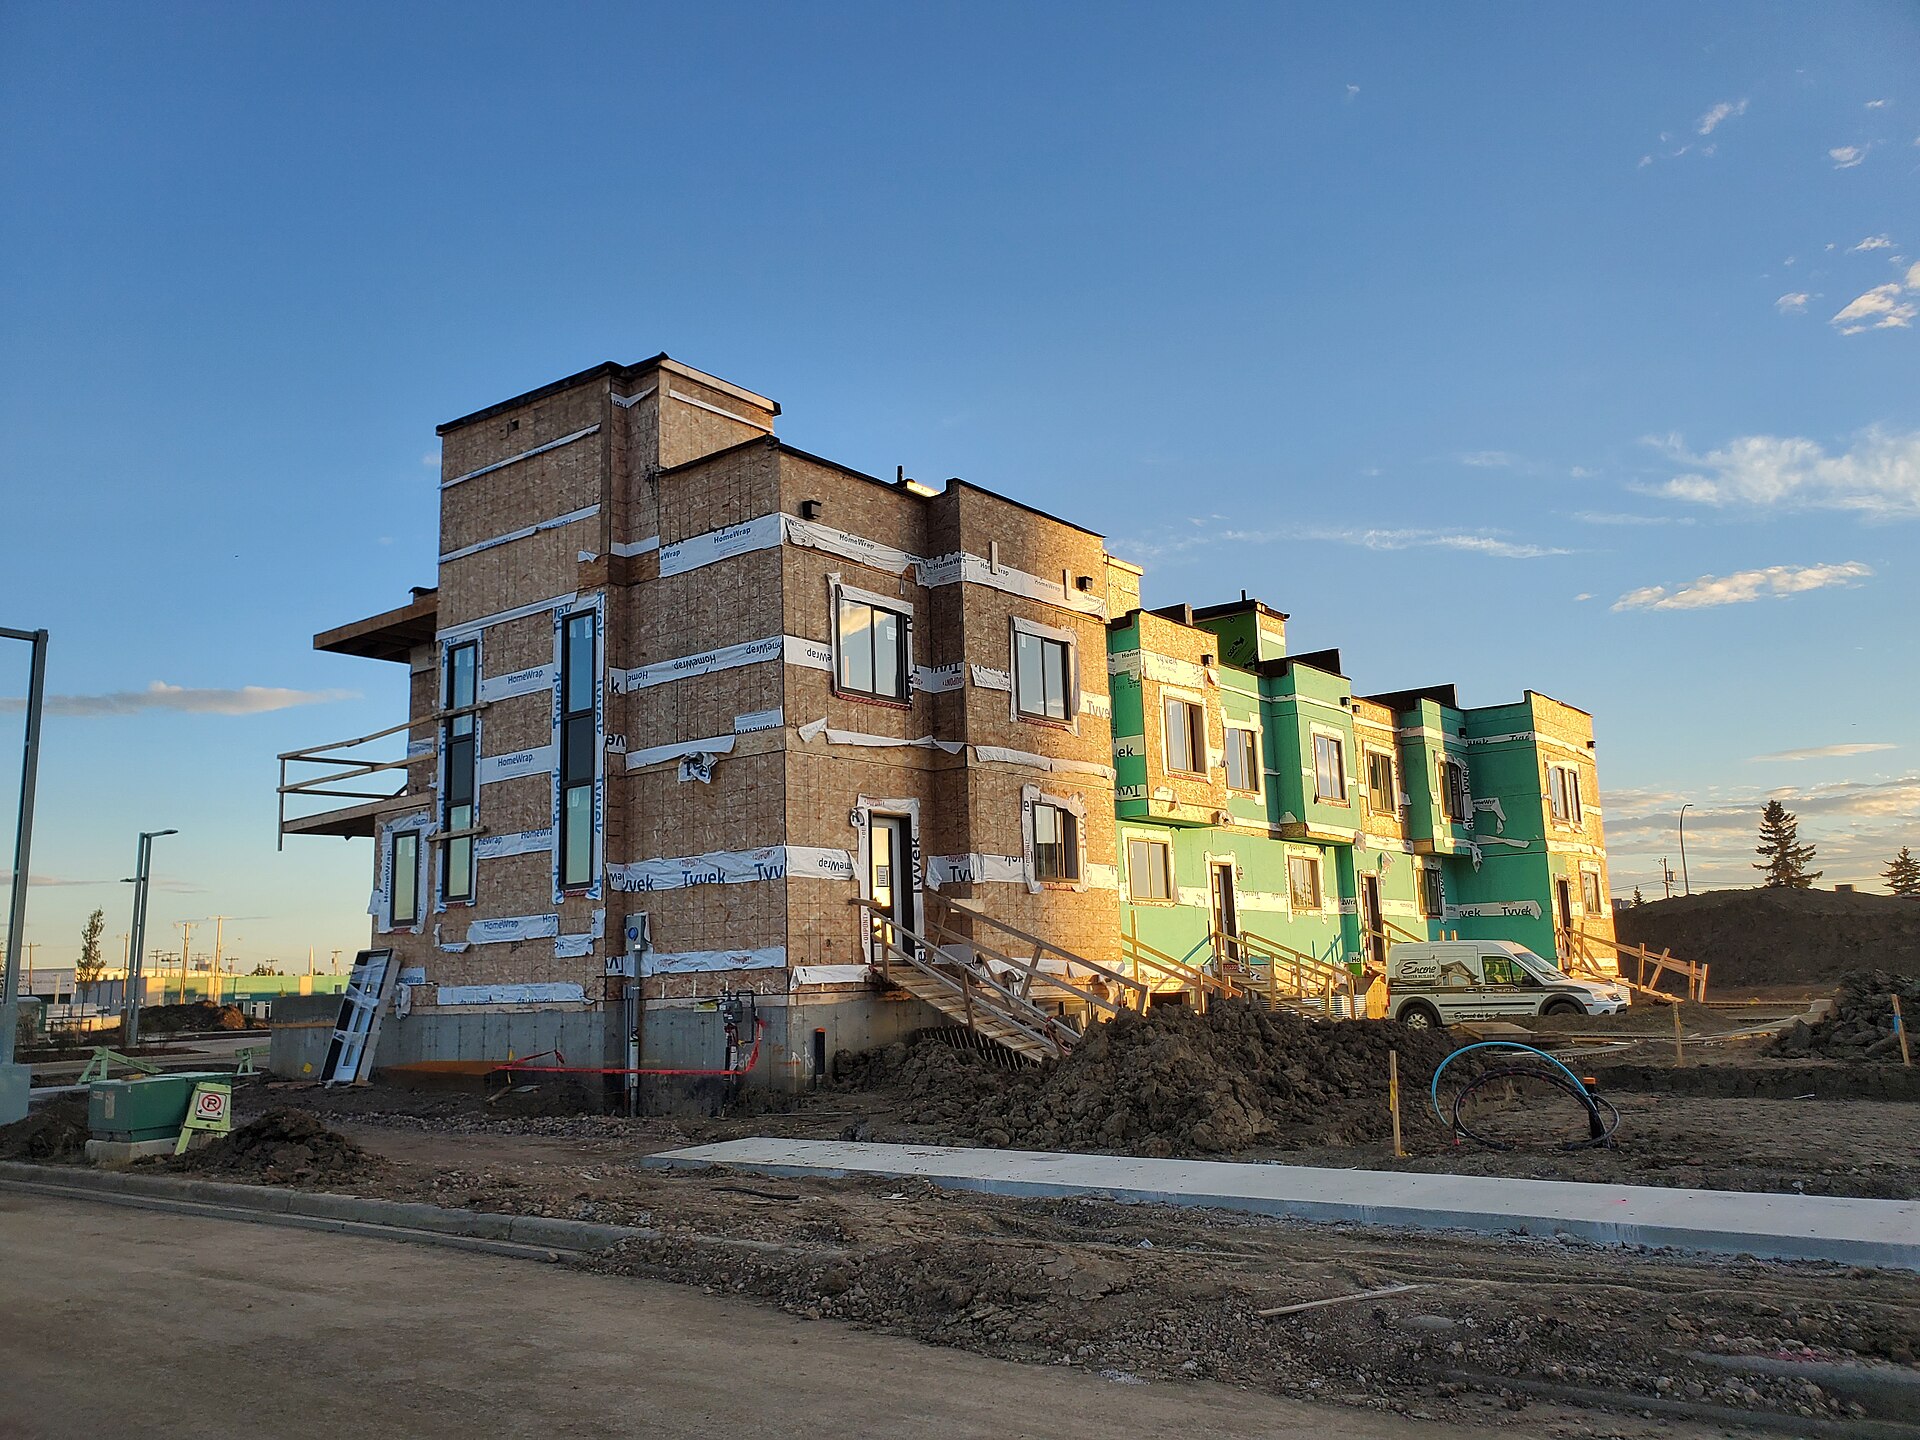
New bungalows are less common than new two-storey homes because they use more land per square foot. You’ll often find them in adult-lifestyle communities, smaller towns in Simcoe and Durham, and as bungalow townhomes in newer subdivisions.
How pre-construction deposits and payments work
Builders rarely ask for the full down payment at once. Instead, you pay a deposit schedule spread over several months. The exact amounts and dates are set out in your agreement.
Your deposit sits with the builder or in trust while the home is built. You don’t earn much on that money, and you can’t easily get it back if you change your mind. That’s why it should come from savings you won’t need for an emergency.
Before you sign, ask these questions:
- How much is due at signing, and when are the later deposits due?
- How are deposits protected if the project is cancelled?
- What upgrades are included, and what will cost extra?
- Which closing charges are capped, and which aren’t?
Upgrades are where budgets often slip. Flooring, kitchen finishes and a finished basement can add up quickly at the design centre, so set a firm limit before your appointment.
The benefits of a pre-construction bungalow
- Tax relief for first-time buyers. The federal First-Time Home Buyers’ GST rebate offers full GST relief, up to $50,000, on new homes up to $1,000,000, phasing out between $1M and $1.5M.
- Ontario HST relief. For agreements signed April 1, 2026 to March 31, 2027, a broader Ontario rebate gives up to $130,000 in total HST relief on new homes.
- Longer amortization. Any buyer of a newly built home can get a 30-year amortization on an insured mortgage.
- Time to save. Staged deposits give you months or years to build your down payment.
- New systems and warranty. Your furnace, roof and windows are new, and Ontario new homes come with a builder warranty backed by Tarion.
These rebates apply to new builds only. They don’t apply to resale bungalows. Confirm your eligibility with your lawyer or accountant.
The risks you need to weigh
Delays
Construction delays are common. Permits, labour and supply issues can push closing back. If you’re selling your current home, line up a backup plan for where you’ll live.
Market changes
You agree on a price today and close later. If values fall, your home may appraise for less than you paid, and the lender may lend less. As of August 2026, the GTA average price was down 2.7% year over year, a reminder that prices can move both ways.
Qualifying at closing
You need to qualify for your mortgage when you close, not just when you sign. If rates, income or debts change, your approval can change too.
Extra closing costs
New homes often carry adjustments for things like utility hookups, development charges and Tarion enrolment. Ask for a list of capped and uncapped charges in writing.
Pre-construction vs resale bungalow
| Factor | Pre-construction | Resale |
|---|---|---|
| Move-in timing | Uncertain, often years | Set closing date |
| New-home tax relief | May qualify | Not eligible |
| Lot size | Often smaller | Often larger, especially older homes |
| Condition | Brand new with warranty | Varies; inspection is key |
| Neighbourhood | Still developing | Established trees, schools, services |
Our post on older bungalows vs new builds looks at the resale side in more detail.
How to decide if pre-construction is right for you
Ask yourself these questions honestly:
- Can I wait an unknown amount of time to move in?
- Can I afford the deposit schedule without draining my emergency fund?
- Will I still qualify for a mortgage if rates rise before closing?
- Do I qualify for first-time buyer or new-home rebates?
- Does the builder have a solid track record on past projects?
Bungalow tip: Visit a builder’s finished communities and talk to neighbours about build quality and how the builder handled warranty claims.
Frequently asked questions
Can I get the GST rebate on a resale bungalow?
No. The federal First-Time Home Buyers’ GST rebate applies only to new homes. Resale homes are not eligible.
What happens if my pre-construction closing is delayed?
Ontario’s new home warranty program includes delayed closing protections. Your lawyer can explain what applies to your agreement.
Do I need a lawyer for a pre-construction purchase?
Yes, you should have a real estate lawyer review the agreement before you sign. Builder contracts are long and favour the builder.
Can I sell a pre-construction home before closing?
Sometimes, through an assignment sale, if the builder allows it. Many builders restrict or charge fees for assignments.
The bottom line
Pre-construction can make sense for patient buyers who qualify for 2026’s new-home rebates and want a modern bungalow. It’s a poor fit if you need certainty on timing or can’t handle market swings.
Compare both options side by side, and set up new-listing email alerts so you also see resale bungalows as they hit the market.
The newest bungalows on the market
Fresh listings, updated every 15 minutes.
 $525,00041 Fox Trail Drive, St. Catharines3 bed · 2 bath · 462 - Rykert/VansickleCourtesy of RE/MAX NIAGARA REALTY LTD, BROKERAGE
 $459,9001737 2nd Street W, Cornwall3+1 bed · 2 bath · 717 - CornwallCourtesy of RE/MAX AFFILIATES MARQUIS LTD.
 $938,00052 Devins Drive, Aurora3 bed · 2 bath · Aurora HeightsCourtesy of REAL ONE REALTY INC.
 $349,900109 Powerview Avenue, St. Catharines3 bed · 1 bath · 458 - Western HillCourtesy of ROYAL LEPAGE NRC REALTY
 $999,00022 Avondale Crescent, Aurora4 bed · 3 bath · Aurora VillageCourtesy of RE/MAX HALLMARK REALTY LTD.
 $819,9002409 Whaley Drive, Mississauga3 bed · 2 bath · CooksvilleCourtesy of SUTTON GROUP - SUMMIT REALTY INC.