Renting vs buying in the GTA comes down to upfront cash, monthly costs and how long you’ll stay. Buying a bungalow takes a significant down payment and closing costs, but it builds equity over time. Renting keeps your cash free and your options open. As of September 2026, a calmer market and lower rates than a few years ago have made buying more realistic for some households.
Key takeaways
- As of August 2026, the GTA median price was $850,000.
- Buying inside Toronto adds a municipal land transfer tax.
- Upfront costs are the biggest hurdle for most buyers.
- Compare total monthly costs, not just rent vs mortgage.
Where the GTA market stands in 2026
Based on TRREB data for August 2026, the average GTA home price was $993,410, down 2.7% year over year. The median price was $850,000, and homes took an average of 51 days to sell.
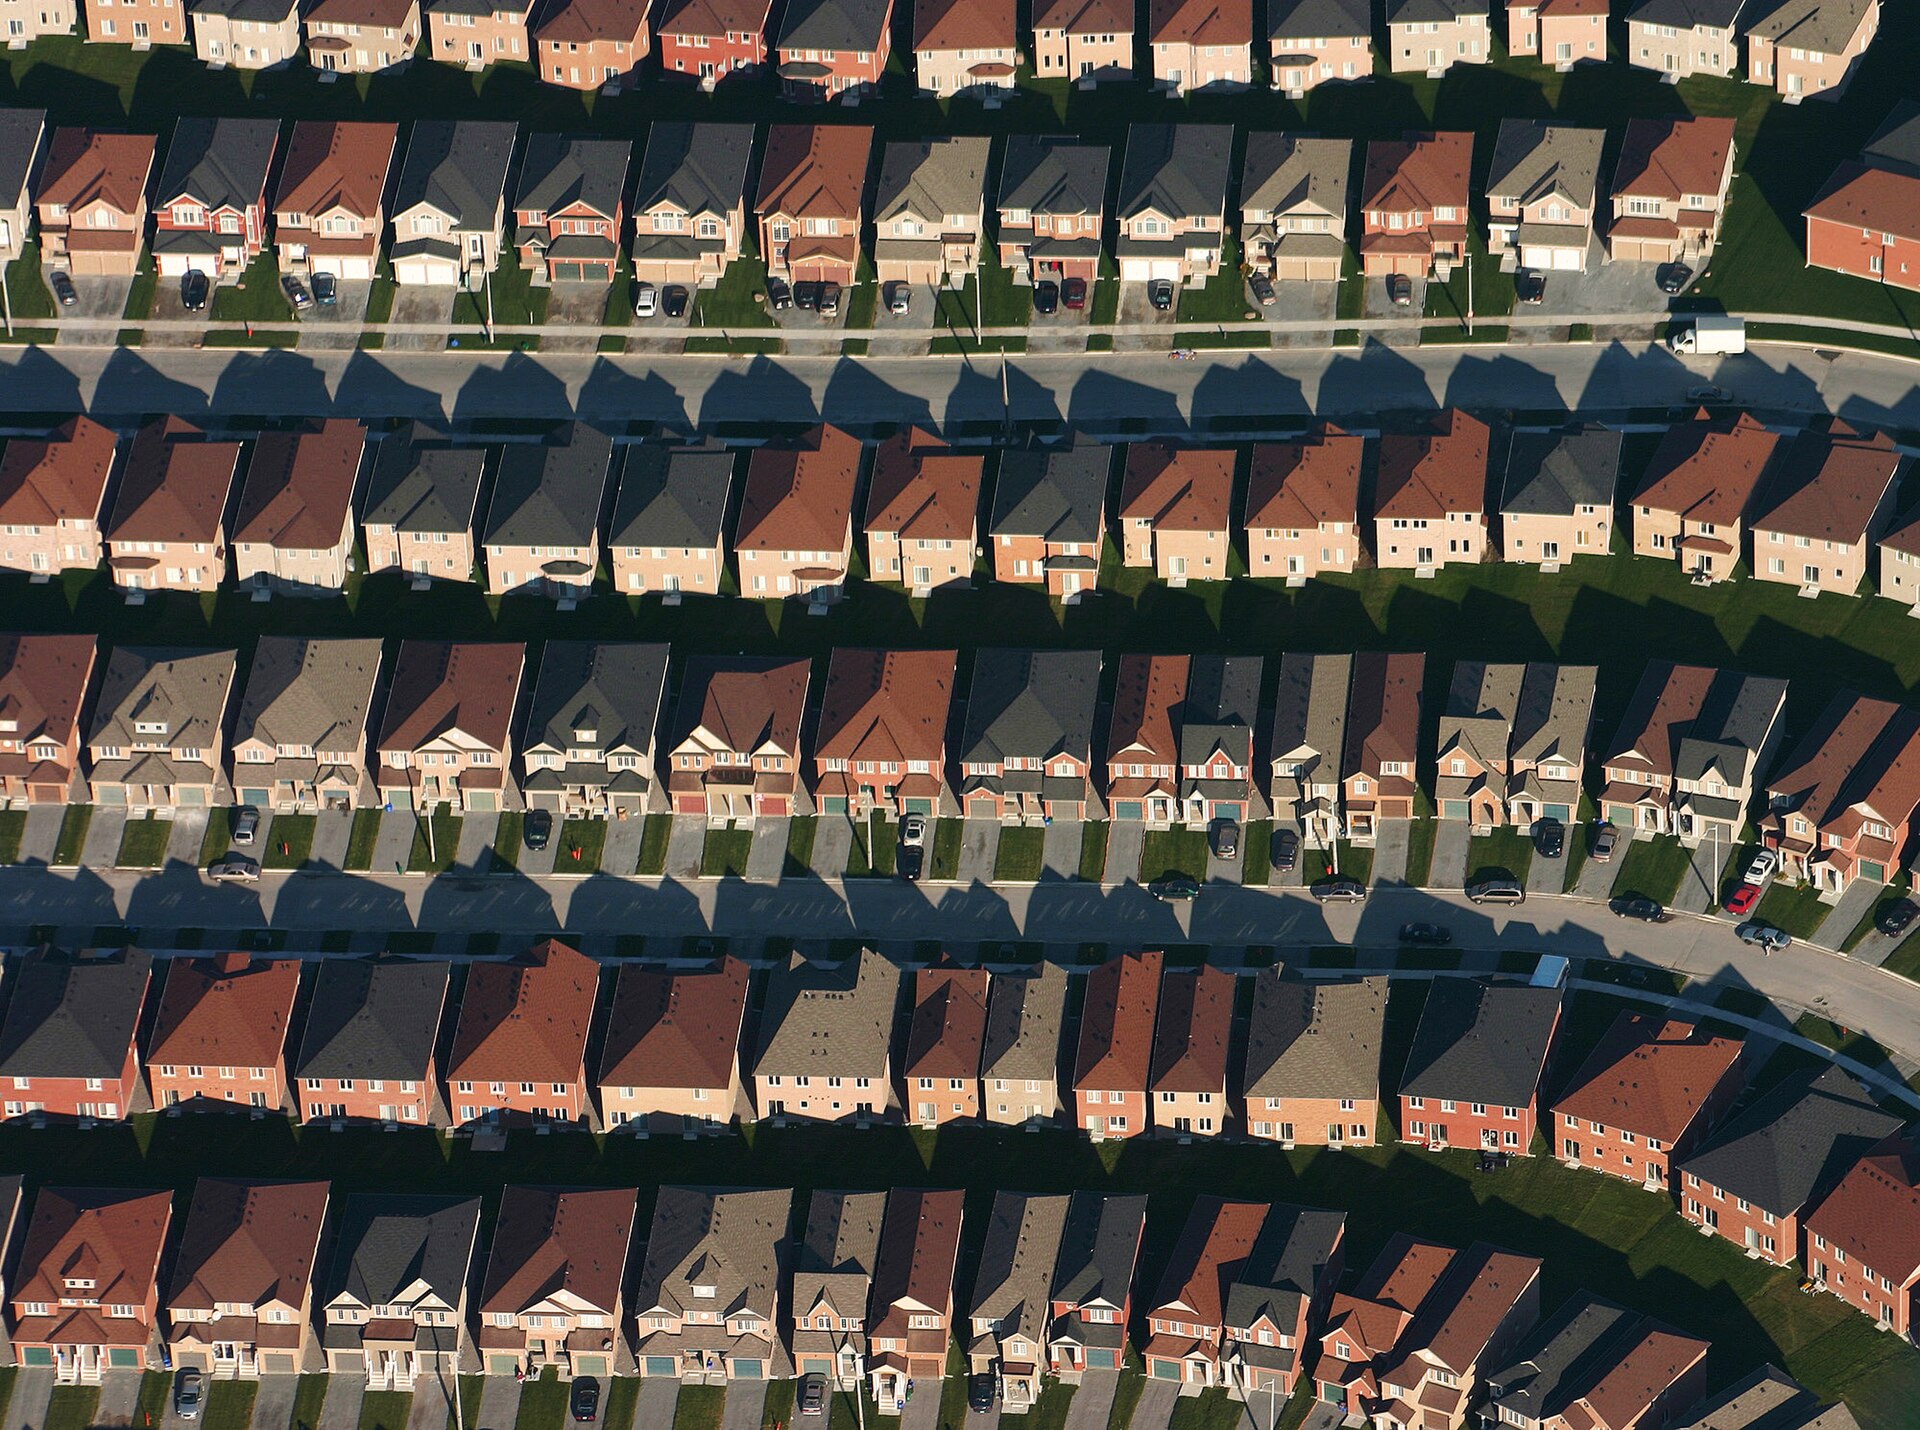
New listings were down 14.1% from a year earlier, so supply is tightening. The market is described as moving toward balance. For buyers, that means more time to decide and more room to negotiate than during the rush years.
On the financing side, the Bank of Canada held its policy rate at 2.25% on September 2, 2026. Typical advertised 5-year fixed rates are in the mid-4% range.
The upfront cost of buying a bungalow
Let’s use the August 2026 GTA median of $850,000 as an example. These figures are illustrations, not quotes.
Down payment
The minimum is 5% on the first $500,000 ($25,000) plus 10% on the next $350,000 ($35,000). That’s a minimum of $60,000. With less than 20% down, you’ll also pay mortgage default insurance, which is usually added to the mortgage.
Land transfer tax
| Where you buy | Approximate land transfer tax on $850,000 |
|---|---|
| Outside Toronto (e.g. Brampton, Vaughan, Oshawa) | About $13,475 provincial tax |
| Inside the City of Toronto | About $26,950 (provincial plus municipal) |
First-time buyers can get an Ontario refund of up to $4,000. Inside Toronto, they can also get a municipal rebate of up to $4,475. That would bring a first-time buyer’s total on an $850,000 Toronto home down to about $18,475.
Other closing costs
Budget for legal fees, title insurance, a home inspection and property tax adjustments. A common rule of thumb is 1.5% to 4% of the price on top of your down payment, with Toronto at the higher end.
The monthly cost of owning vs renting
Comparing rent to a mortgage payment alone is a common mistake. Here’s what each side really includes:
| Monthly cost | Owner | Renter |
|---|---|---|
| Housing payment | Mortgage (part interest, part principal) | Rent |
| Property tax | Yes | No (built into rent) |
| Insurance | Home insurance | Tenant insurance |
| Maintenance | Yes, set aside money monthly | Minor, if any |
| Utilities | All | Depends on the lease |
Remember that the principal part of your mortgage builds equity. It’s a cost to your cash flow, but it’s also savings.
Owners should also set aside money every month for repairs and replacements. Roofs, furnaces, windows and driveways all wear out, and older GTA bungalows may need several of these within a few years of buying. Ask the seller for the age of each major item so you can plan.
Renters face their own risk: rent can rise between tenancies, and a landlord may sell or reclaim the home for their own use, with proper notice and compensation. Factor that uncertainty into your comparison.
When buying in the GTA makes more sense
- You plan to stay in the same area for several years.
- You have your down payment, closing costs and an emergency fund.
- You qualify comfortably under the stress test at the higher of your rate plus 2% or 5.25%.
- You want a basement unit to help with costs.
- You qualify for first-time buyer help like the FHSA or the RRSP Home Buyers’ Plan.
Looking outside Toronto can also help. Cities in Durham, Simcoe and Niagara often offer more bungalow for the money, and you avoid the Toronto land transfer tax. Explore the Durham Region or Simcoe Region pages.
When renting in the GTA makes more sense
- You might move within a few years.
- Your savings would be drained by the down payment and closing costs.
- Your income is new, irregular or about to change.
- You’re not sure which neighbourhood you want long term.
If you rent, make your savings work. Contributing to an FHSA lets you save $8,000 a year, up to $40,000, with tax-deductible contributions and tax-free qualifying withdrawals.
Bungalow tip: A bungalow with a legal basement unit can change the math. Rent from the unit can offset a big part of your monthly costs. See bungalows with a separate entrance.
Frequently asked questions
Is it better to rent or buy in Toronto in 2026?
It depends on your savings, income and timeline. A more balanced market and lower rates than recent peaks help buyers, but renting still suits people who need flexibility.
How much do I need to buy an $850,000 bungalow in the GTA?
The minimum down payment is $60,000, plus closing costs. Land transfer tax alone is about $13,475 outside Toronto before any first-time buyer refund.
Do I pay Toronto land transfer tax in Mississauga or Brampton?
No. The municipal land transfer tax applies only to properties inside the City of Toronto.
Should I wait for prices to drop before buying?
No one can time the market reliably. Buy when your finances are ready and you find the right home at a fair price.
The bottom line
In the GTA, buying a bungalow takes serious upfront cash but builds equity, while renting keeps you flexible. Run the full numbers, including land transfer tax and maintenance, before deciding.
Try our mortgage and land transfer tax calculators, and speak with a mortgage agent to see what you’d qualify for.
Bungalows for sale in Toronto and Brampton
Live listings from the places in this article.
 $1,500,00097 Estelle Avenue, Toronto3+4 bed · 7 bath · Willowdale EastCourtesy of RE/MAX REALTRON REALTY INC.
 $699,0007 Twenty Second Street, Toronto3+3 bed · 3 bath · Long BranchCourtesy of RE/MAX PREMIER INC.
 $945,000257 John Tabor Trail E, Toronto3+2 bed · 2 bath · MalvernCourtesy of RE/MAX ATRIUM HOME REALTY
 $969,000375 Bartley Bull Parkway, Brampton3+1 bed · 2 bath · Bram EastCourtesy of CENTURY 21 MILLENNIUM INC.
 $789,000173 Fairhill Avenue, Brampton2+2 bed · 3 bath · Fletcher's MeadowCourtesy of CENTURY 21 MILLENNIUM INC.
 $849,00059 Royce Avenue, Brampton4 bed · 4 bath · Downtown BramptonCourtesy of RE/MAX GOLD REALTY INC.